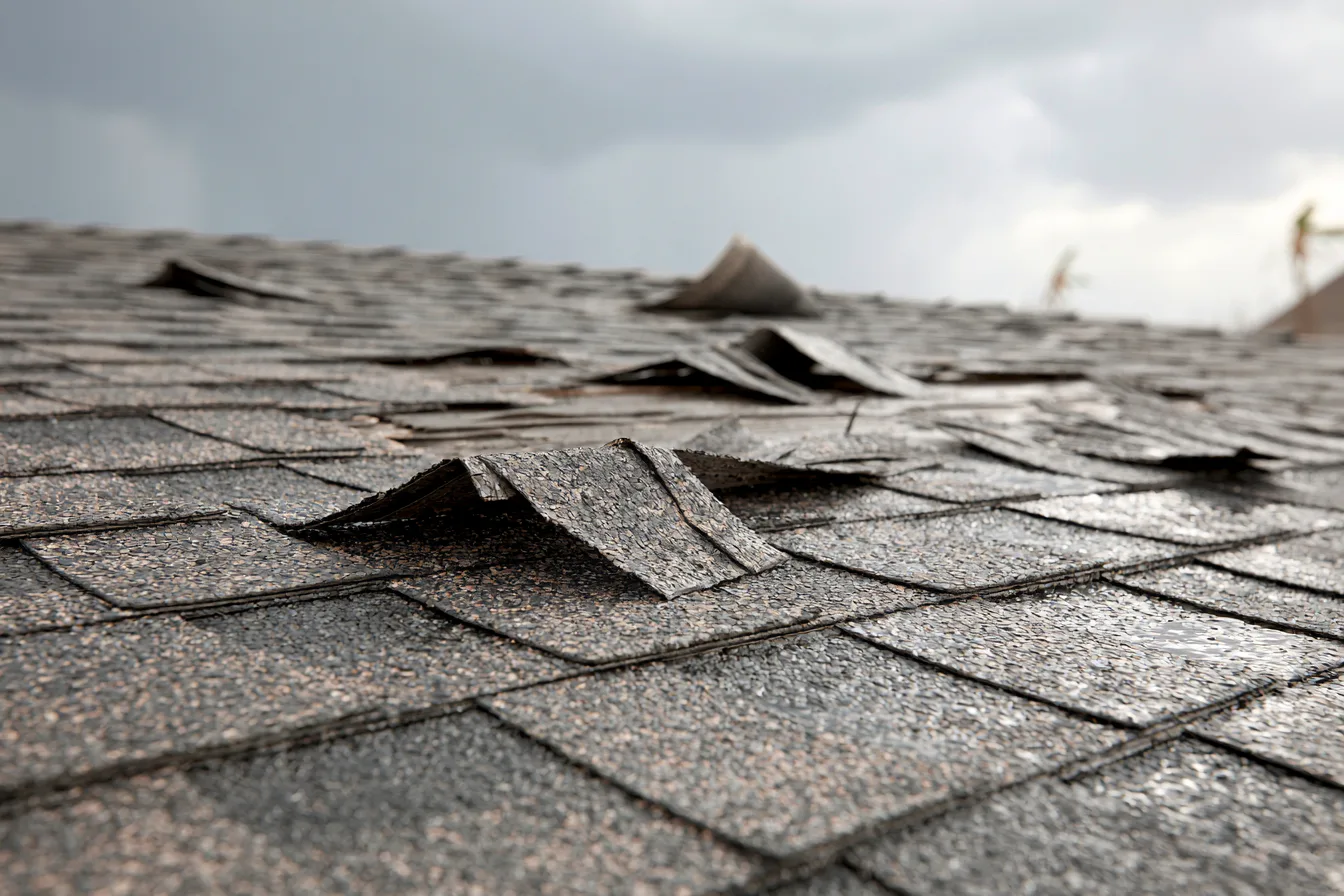
Roof Insurance Claims in Inola, OK
Understand the roof condition, the policy terms and the owner’s share of the project without assuming a claim will pay for a new roof.
Separate the roof decision from the coverage decision
Roof work and an insurance claim answer different questions. The roofer assesses condition and work; the insurer determines coverage under the policy. Keeping those decisions clear helps you understand both the proposed work and the part of its cost you may need to cover.
For an active problem, safe protection and the roof condition come first. The Oklahoma Insurance Department’s guidance explains reporting a loss, limiting further damage and understanding the policy’s valuation method.
What the coverage words change
Definitions and claim context: Oklahoma Insurance Department. Your actual policy and insurer’s decision govern.
Keep roof work and the claim moving together
Address the immediate condition
Stay clear of dangerous areas and arrange appropriate protection where the building is exposed. Save records of necessary temporary work for the claim conversation.
Report and establish the facts
The policyholder reports the loss to the insurer. Known dates, safe photographs and the observed condition support the discussion without proving every mark came from one event.
Understand the scope and payment
The roof-work proposal and insurer’s covered scope may differ. Policy limits, deductible and depreciation need to be understood before treating an anticipated payment as the whole project budget.
A deductible is part of the owner’s budget
A deductible is not a contractor discount. It is part of the policyholder’s responsibility under the policy. A percentage deductible is tied to the basis specified in the policy, not necessarily a percentage of the repair bill.
A claim’s value depends on covered damage, the policy’s valuation method and the deductible together. This site cannot determine the outcome from a roof’s age or a nearby storm report.
For claim questions, use the Oklahoma Insurance Department’s storm FAQs and your insurer’s actual policy information.
Start with a roof condition question
A free inspection can help explain the visible roof condition. It does not promise insurance approval or assign damage to a particular storm.